Thursday, September 17

Musikana waHwinza Maloti Akadzvanya Machende Emurume Akamubira Phone & US$2k

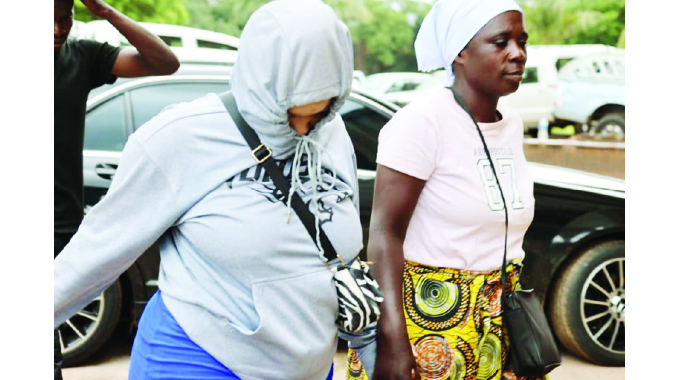
ZIMDANCEHALL chanter Hwinza’s girlfriend, Millicent Chimonyo, is accused of stealing an iPhone 13 Pro and US$2000 after squeezing the private parts of the owner of the phone and cash.


She said she does not want a lawyer to represent her and will represent herself during the trial. Millicent appeared in court before magistrate, Dennis Mangosi, who remanded her in custody pending her bail application today. Allegations are that on November 16, Millicent called the complaint, Lecious Chipangura, and told him to bring baby clothes and cosmetics.


He is in the business of selling clothes and cosmetics. Lecious is known to Millicent as someone who keeps cash on a regular basis. As soon as Lecious entered a Nissan Note, owned and driven by Millicent, who was in the company of two accomplices, she drove the car out of town. Lecious is said to have resisted this move.


Millicent pulled off the road along Simon Mazorodze Road, got out of the car and grabbed Lecious’ private parts while her accomplices searched him.They forcibly took an iPhone 13 Pro and US$2 000 from his pockets. One of the suspects then hit him with a wheel spanner and they pushed him out of the car.

  • Share:

Info News

Best Business Credit Cards for Large Monthly Spending

Business owners spending heavily each month often leave enormous value on the table.

rnrn

Travel rewards. Cashback programs. Expense tracking. Employee card controls.

rnrn

The right credit card strategy can improve cash flow while generating significant financial benefits.

rnrn

That’s why many companies search for the best business credit cards for large monthly spending.

rnrn

But not all premium business cards deliver equal value.

rnrn

What High-Spending Businesses Should Prioritize

rnrn

A flashy rewards offer means nothing if the card creates operational headaches later.

rnrn

Experienced business owners evaluate several important factors.

rnrn

Spending Limits and Flexibility

rnrn

Businesses with large operating expenses often need:

rnrn
    rn
  • High spending limits
  • rn
  • Flexible payment structures
  • rn
  • Multiple employee cards
  • rn
  • Fraud monitoring systems
  • rn
rnrn

Operational flexibility matters heavily.

rnrn

Rewards Structures

rnrn

Some cards favor:

rnrn
    rn
  • Travel spending
  • rn
  • Advertising purchases
  • rn
  • Fuel expenses
  • rn
  • Technology purchases
  • rn
  • Office supply spending
  • rn
rnrn

The best business credit card depends on where the company spends most.

rnrn

Expense Management Tools

rnrn

Modern business cards increasingly integrate with:

rnrn
    rn
  • Accounting software
  • rn
  • Expense reporting systems
  • rn
  • Payroll platforms
  • rn
  • Financial dashboards
  • rn
rnrn

Automation saves time for finance teams.

rnrn

Risks Businesses Must Understand

rnrn

Large spending limits can create dangerous financial habits.

rnrn

Poor management may lead to:

rnrn
    rn
  • High interest costs
  • rn
  • Cash flow pressure
  • rn
  • Debt accumulation
  • rn
  • Credit score damage
  • rn
rnrn

Rewards never justify reckless spending.

rnrn

Why Premium Business Cards Have High CPC Keywords

rnrn

Business credit card customers often generate substantial long-term revenue for financial institutions.

rnrn

Banks compete aggressively for high-spending business clients.

rnrn

That’s why these SEO keywords attract strong advertiser competition.

rnrn

Final Takeaway

rnrn

The best business credit cards for large monthly spending combine strong rewards, operational flexibility, fraud protection, and financial management tools.

rnrn

Smart businesses use credit strategically instead of emotionally.

rnrn

That difference matters long term.

rnrn

FAQ

rnrn

What business credit card rewards are most valuable?

rnrn

It depends on company spending patterns and operational needs.

rnrn

Do business credit cards affect personal credit?

rnrn

Some issuers report activity to personal credit bureaus while others do not.

rnrn

Are premium annual fees worth it?

rnrn

For high-spending businesses, rewards and benefits may outweigh annual costs.

rn

SEO Meta Title Debt Consolidation Loans: Pros, Cons, and Comparison Tips

Debt consolidation can sound like an easy solution: combine several debts into one payment and possibly lower the interest rate. For some borrowers, that can be helpful. For others, it only moves debt around while the balance continues to grow. The difference depends on the loan terms, fees, spending habits, income stability, and payoff discipline.

A debt consolidation loan is usually a personal loan used to pay off credit cards, medical bills, store cards, payday loans, or other unsecured debts. After the old balances are paid, the borrower makes one fixed monthly payment to the new lender. The main appeal is simplicity. One due date, one payment, and one payoff timeline can make budgeting easier.

The biggest potential benefit is a lower interest rate. Credit cards often charge variable rates that can rise over time. A fixed-rate personal loan may offer a predictable payment and a defined end date. If the new loan has a lower rate and you avoid new debt, consolidation can reduce interest costs and speed up payoff.

However, the monthly payment is not the only number to review. A longer repayment term can lower the monthly payment while increasing total interest paid. For example, stretching debt over several years may feel easier each month but cost more overall. Always compare total repayment, not just the payment amount.

Fees matter too. Some lenders charge origination fees, late fees, returned payment fees, or prepayment penalties. An origination fee may be deducted from the loan amount, which means you receive less money than expected. Compare the annual percentage rate because it includes certain finance charges and gives a better apples-to-apples view than the interest rate alone.

Credit score impact can go in different directions. Applying for a loan may create a hard inquiry. Opening a new account can reduce the average age of credit. However, paying down credit card balances may improve credit utilization, which can help some borrowers over time. The biggest factor remains making on-time payments.

The main risk is running up the old credit cards again. If you consolidate balances and continue using cards without a budget, you may end up with the consolidation loan plus new credit card debt. Before taking a loan, create a spending plan and decide whether to close cards, lower limits, or keep cards open but unused.

Not everyone qualifies for a low rate. Lenders may review credit score, income, debt-to-income ratio, employment history, payment history, and existing balances. Borrowers with stronger credit often receive better terms. If the offers are high-interest, consolidation may not save money.

Alternatives include a balance transfer credit card, nonprofit credit counseling, a debt management plan, negotiating with creditors, budgeting changes, side income, or a structured debt snowball or debt avalanche method. Balance transfers may offer promotional rates, but fees and deadlines matter. Missing the promotional payoff date can lead to higher interest.

Before choosing any offer, write down every debt: creditor, balance, interest rate, minimum payment, due date, and payoff priority. Then compare three scenarios: keeping current payments, using a consolidation loan, and using another strategy. A simple spreadsheet can reveal whether consolidation truly saves money.

Ask lenders these questions: Is the rate fixed or variable? What is the APR? Are there origination fees? Is there a prepayment penalty? What is the total repayment amount? When are funds sent? Can the lender pay creditors directly? What happens if I miss a payment? Are there hardship options?

Debt consolidation works best when it is part of a larger debt payoff plan. The loan should create a clear path out of debt, not a temporary break from the pressure. If the payment fits the budget, the rate is lower, and the borrower stops adding new balances, consolidation can be a useful tool. If not, it may delay the real problem.