Tuesday, November 03

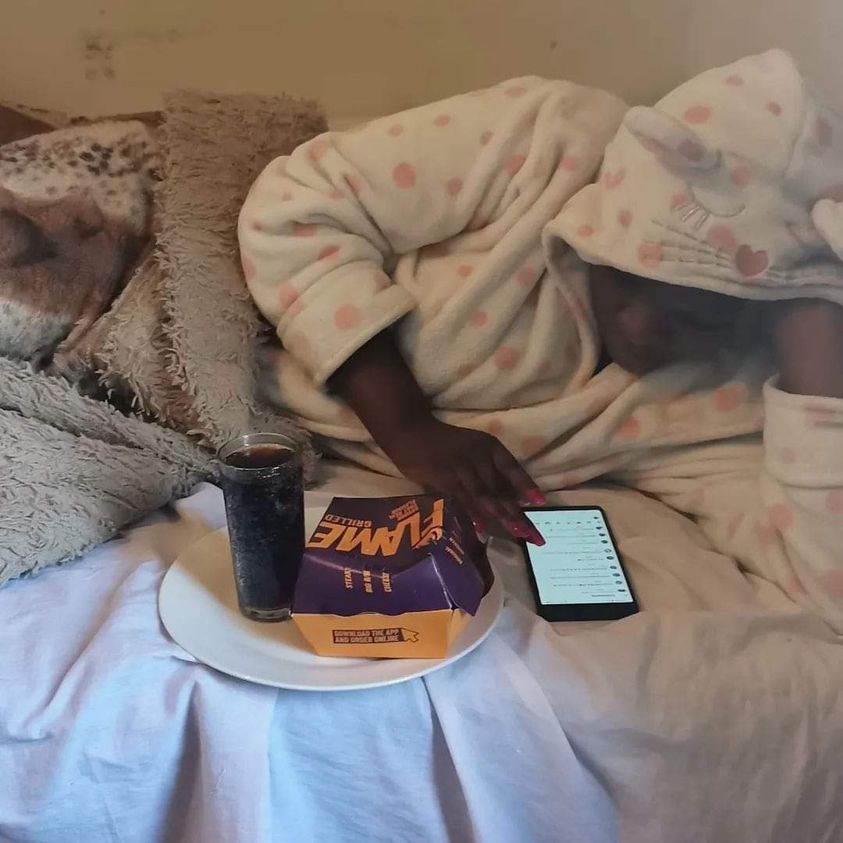
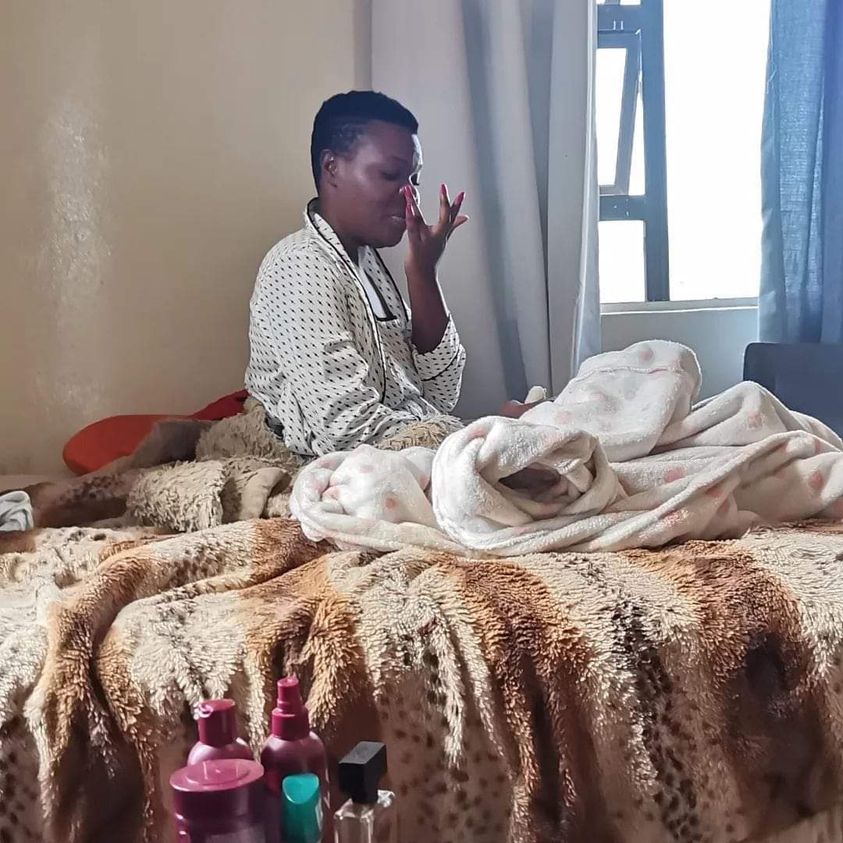
Obina Ofumura Mai TT Pavairara Mu One Bedroom Vachifuga Gumbeze Remaguru


She never wanted me to take any pictures in my one room apartment because of her status. She said and I quote "Baby the reason I always want to stay in a hotel whenever I come visiting you is very simple... I can't be seen coming out of such a place. Imagine what my fans would say if they saw me coming out of that your place"... Those were her words to me. Remember she also told you guys that I ran away with her property she bought... Let me correct that one... Every damn thing in my little one room apartment was bought with my blood and sweat... Not one thing was bought by her... Tune for more.

  • Share:

Info News

SEO Meta Title Credit Repair vs Credit Counseling: Compare Your Options

When credit problems become stressful, two options often appear in search results: credit repair and credit counseling. They sound similar, but they are not the same service. Credit repair focuses on disputing inaccurate, incomplete, or unverifiable information on credit reports. Credit counseling focuses on budgeting, debt repayment, and financial education. Knowing the difference can help you avoid scams and choose the right help.

Credit repair companies often advertise help with removing negative items from credit reports. Legitimate credit repair is based on your legal right to dispute inaccurate information. If a late payment, collection, account balance, personal detail, or account status is wrong, you can dispute it with the credit bureaus and the company that furnished the information.

However, accurate negative information usually cannot be removed simply because it hurts your score. Late payments, collections, bankruptcies, and charge-offs may remain on credit reports for legally allowed periods if they are accurate. Be cautious with any company that promises a specific score increase, guaranteed removals, or a new credit identity.

Credit counseling is different. A nonprofit credit counseling agency can review income, expenses, debts, and goals. Counselors may help build a budget, explain credit reports, suggest repayment strategies, and discuss whether a debt management plan makes sense. A debt management plan may consolidate payments through the counseling agency and sometimes reduce interest rates or fees with participating creditors.

Credit counseling can be useful when the main problem is debt affordability. If you are making minimum payments, falling behind, or using one card to pay another, a counselor can help create a structured plan. Credit repair alone will not solve unaffordable debt.

Credit repair can be useful when the main problem is inaccurate reporting. For example, an account that does not belong to you, a debt listed twice, an incorrect late payment, a paid account still shown as unpaid, or outdated information may be disputable. You can file disputes yourself for free, but some people hire help because they do not want to manage the paperwork.

Before paying for credit repair, understand your rights. In the United States, credit repair companies must follow federal rules, including restrictions on misleading claims and upfront fees. You should receive a written contract, cancellation rights, and clear information about what the company will do. If a company pressures you, asks you to lie, tells you to dispute everything, or suggests using a different Social Security number, walk away.

A strong credit rebuilding plan often includes both cleanup and behavior changes. Start by pulling credit reports from the major bureaus. Review personal information, open accounts, closed accounts, collections, public records, inquiries, balances, and payment history. Highlight anything inaccurate and gather supporting documents.

Next, pay every current bill on time. Payment history is a major scoring factor. Set up reminders or autopay for minimum payments. Then focus on credit utilization, which is the percentage of available revolving credit being used. Lower balances can help improve scores over time.

Avoid opening too many new accounts at once. New inquiries and new accounts can lower scores temporarily. Instead, build a steady pattern: pay on time, reduce balances, keep older accounts in good standing, and monitor reports for errors.

If you have no active credit, a secured credit card or credit-builder loan may help, but fees and terms matter. Choose products from reputable banks or credit unions and avoid high-fee cards that drain your budget.

The right choice depends on the root problem. Choose credit repair if the issue is inaccurate reporting. Choose credit counseling if the issue is debt management, budgeting, or missed payments. Use both if you have errors and unaffordable debt. Most importantly, avoid anyone promising instant results. Real credit improvement takes accurate reporting, consistent payments, lower debt, and time.

Mortgage Refinancing: Lower Your Payments and Save More Over Time

Mortgage refinancing is one of the most effective financial strategies homeowners can use to reduce monthly payments, lower interest rates, or access home equity. By replacing your existing mortgage with a new loan that has better terms, you can potentially save thousands of dollars over the life of your loan. Whether you're looking for low interest mortgage rates, cash-out refinancing options, or fixed-rate home loans, understanding how refinancing works is essential before making a decision.

rnrn

Refinancing is especially popular when interest rates drop or when a homeowner’s credit score improves. Many borrowers take advantage of refinancing to switch from an adjustable-rate mortgage (ARM) to a fixed-rate mortgage, providing long-term financial stability. Others use cash-out refinancing to tap into their home’s equity, allowing them to fund renovations, consolidate debt, or invest in other opportunities. While refinancing offers many benefits, it’s important to carefully evaluate your goals and financial situation to ensure it’s the right move.

rnrn

How Mortgage Refinancing Works

rnrn

When you refinance your mortgage, you essentially take out a new loan to pay off your existing one. The new loan comes with updated terms, including a new interest rate, repayment period, and monthly payment. Lenders will evaluate your financial profile, including your credit score, income, debt-to-income ratio, and home value, to determine eligibility.

rnrn

The process typically involves submitting an application, providing documentation, and undergoing a home appraisal. Once approved, the new loan replaces your current mortgage, and you begin making payments under the new terms. Many homeowners search for best mortgage refinance lenders to ensure they secure the most favorable deal.

rnrn

Benefits of Refinancing Your Mortgage

rnrn

One of the biggest advantages of refinancing is the opportunity to secure a lower interest rate. Even a small reduction in your rate can lead to significant savings over time. Lower monthly payments can free up cash flow, making it easier to manage other financial responsibilities.

rnrn

Another benefit is the ability to shorten your loan term. For example, switching from a 30-year mortgage to a 15-year loan allows you to pay off your home faster and reduce total interest costs. Additionally, cash-out refinancing gives homeowners access to funds for major expenses, often at lower interest rates than personal loans or credit cards.

rnrn

When Is the Right Time to Refinance?

rnrn

Timing plays a critical role in refinancing decisions. Homeowners should consider refinancing when interest rates are significantly lower than their current rate. A general rule of thumb is that reducing your rate by at least 1% can make refinancing worthwhile.

rnrn

Improving your credit score can also help you qualify for better loan terms. If your financial situation has improved since you first obtained your mortgage, refinancing could provide substantial savings. Additionally, homeowners planning to stay in their property long-term are more likely to benefit from refinancing, as it takes time to recover closing costs.

rnrn

Costs and Considerations

rnrn

While refinancing offers many benefits, it’s important to consider the associated costs. These may include application fees, appraisal fees, and closing costs, which can range from 2% to 5% of the loan amount. Calculating your break-even point—the time it takes to recover these costs—is essential before proceeding.

rnrn

Borrowers should also be cautious about extending their loan term, as this can increase the total amount of interest paid over time. Working with a trusted mortgage refinancing company can help you evaluate your options and make an informed decision.

rnrn

Final Thoughts

rnrn

Mortgage refinancing can be a powerful tool for improving your financial situation, but it requires careful planning and research. By understanding the process, comparing lenders, and evaluating your long-term goals, you can make a decision that aligns with your needs. Whether you’re looking to reduce monthly payments or access equity, refinancing offers opportunities for greater financial flexibility.

rnrn


rnrn

Financial experts recommend working with licensed mortgage lenders, certified financial advisors, and reputable home loan providers when considering refinancing options. Professional guidance ensures better loan terms and long-term financial stability.

rn